ZZP and MKB Insurance Requirements by Business Risk
Why Sector Risk Matters More Than Size
When reviewing ZZP insurance requirements or planning cover for a growing company, business owners often assume size is the main pricing factor. In practice, insurers usually look first at sector risk. A solo roofer, electrician, or food producer can face far greater claim exposure than a larger office-based consultancy with ten employees. That is why the nature of the work often matters more than turnover or headcount alone.
Sector risk shapes the chance of injury, property damage, professional mistakes, theft, equipment loss, and digital threats. A hands-on trade may need broader business risk cover because one incident can affect clients, third parties, or expensive sites. By contrast, a low-risk service business may focus more on professional liability, data protection, and income continuity.
Good insurance planning starts with what can go wrong in your trade, not just how big your business looks on paper.
For both ZZP and MKB firms, the smartest starting point is to map daily activities, contract obligations, and client expectations. That makes it easier to choose relevant policies and avoid paying for cover that does not match the actual exposure.
Which Policies Do ZZP Businesses Often Need?
Most self-employed professionals do not need every policy on the market, but many do need a practical core package. The right mix depends on contracts, tools, client demands, and whether the business gives advice, performs physical work, or stores customer data. In many cases, liability insurance is one of the first covers considered because third-party damage claims can be costly even for a one-person operation.
Typical ZZP insurance requirements may include:
Business liability insurance for injury or property damage to others
Professional liability insurance for advice, design, or administrative errors
Equipment or inventory cover for tools, laptops, and stock
Cyber business cover for data breaches, ransomware, and IT recovery
Income protection to help when illness or accident stops the owner from working
Legal expenses cover for contract or client disputes
Not every freelancer needs all six. A web designer may prioritize cyber and professional liability, while a tradesperson may focus on tools and public liability. The goal is to match each policy to the business model, not to buy a generic package.
How Do MKB Insurance Costs Usually Change?
MKB insurance costs often change as a business becomes more complex. Growth can mean more staff, larger contracts, extra vehicles, higher revenue, new premises, or wider geographic activity. Each of those changes may increase the insurer's exposure, which can affect premiums, deductibles, and policy terms. However, rising cost is not always caused by size alone; it is usually driven by how growth changes the actual risk profile.
Claims history also matters. A business with few claims, clear safety procedures, and strong administration may secure better terms than a smaller company with repeated losses. Insurers typically assess factors such as industry type, annual payroll, turnover, security measures, cyber controls, and subcontractor use.
As an MKB business grows, premiums tend to reflect operational complexity rather than growth for its own sake.
Business owners should review policies whenever they add services or enter a riskier market. Underinsurance can leave serious gaps, while outdated cover can mean paying for limits or protections that no longer fit. Regular reviews are one of the simplest ways to keep business risk cover efficient and cost-aware.
Liability, Cyber and Income Risks Mapped
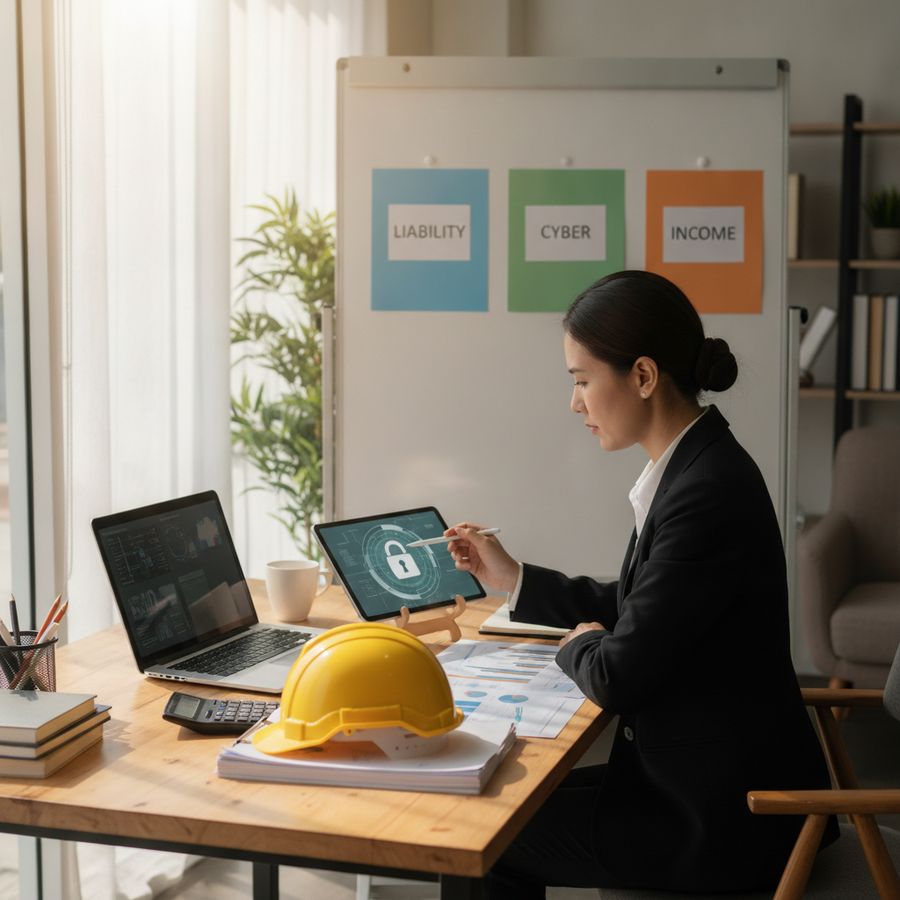
A useful way to choose insurance is to group exposure into three core areas: liability, cyber, and income risk. This makes complex insurance decisions easier for both freelancers and established firms. If your work can injure someone, damage property, trigger a financial loss for a client, or interrupt trading, you already have insurable exposure worth mapping clearly.
Liability insurance usually protects against claims from third parties after bodily injury or property damage. Professional liability can respond when advice, planning, design, or administration causes financial harm. Cyber business cover becomes increasingly important when you handle customer records, payment data, cloud systems, or remote logins. Income risk, meanwhile, concerns what happens if sickness, an accident, or a serious disruption stops the owner or team from operating.
Liability risk: injuries, damaged client property, faulty work
Cyber risk: hacked email, ransomware, data leaks, recovery costs
Income risk: illness, disability, interruption of key operations
By mapping these three areas first, businesses can see where the biggest financial threat sits. That leads to more relevant cover choices and reduces the chance of overlooking a major vulnerability.
Required Documents Speed Up Underwriting
Applying for insurance is usually faster and smoother when the right documents are ready from the start. Underwriters want a clear picture of what the business does, how it operates, and how much risk it presents. Missing details can slow approval, create follow-up questions, or even lead to inaccurate pricing. For that reason, solid preparation is part of good risk management.
Common documents often include company registration details, revenue figures, payroll data, claims history, contract examples, equipment values, and descriptions of services provided. For cyber-related policies, insurers may also ask about backups, antivirus tools, access controls, and incident response processes. Businesses seeking broader business risk cover may need to show health and safety procedures or proof of subcontractor arrangements.
Clear paperwork does more than speed up underwriting — it helps insurers assess the business correctly from day one.
For ZZP professionals, the documentation may be simpler, but accuracy still matters. For MKB firms, organized records can improve insurer confidence and reduce delays during renewals or mid-term adjustments. Good administration also makes it easier to compare options and understand whether the offered cover truly fits the business.
Bundled Cover Can Simplify Administration
For many businesses, combining several policies into one coordinated package makes insurance easier to manage. Rather than tracking separate renewal dates, documents, excess levels, and contact points, owners can centralize administration around a more streamlined arrangement. That is especially helpful for busy ZZP operators and MKB companies that already manage multiple suppliers, invoices, and compliance tasks.
Bundled cover can bring together elements such as liability insurance, property protection, legal expenses, tool cover, and cyber business cover. In some cases, packaging policies may also create a clearer overview of exclusions and help avoid overlaps between separate insurers. Administrative simplicity does not automatically mean cheaper premiums, but it can reduce confusion and save time.
Fewer renewal dates to monitor
More consistent policy documentation
Less risk of duplicated or missing cover
Simpler updates when the business changes
That said, bundled solutions should still be reviewed carefully. A package is only valuable if it reflects real exposure in the business. The best setup balances convenience with tailored protection, rather than forcing every company into the same template.
Choosing Protection by Trade and Exposure
The most effective insurance decisions stem from a detailed understanding of the actual trade, workplace environment, and exposure levels. Whether you're a consultant, café owner, installer, beauty professional, or e-commerce retailer, each faces unique claim patterns. This is why the best coverage isn’t simply determined by business type; it should accurately reflect where work occurs, potential risks, and the possible financial repercussions.
For instance, a contractor may require more robust third-party liability insurance and tool protection, whereas an accountant might prioritize professional errors and data security. A retailer handling online payments may need broader cyber business cover than a local service provider with minimal client data. Additionally, any owner reliant on personal availability should carefully consider continuity protection.
Choosing protection by exposure means insuring the real pressure points of the business, not just following a standard checklist.
This approach also helps control MKB insurance costs by focusing budget where losses would hurt most. In short, the right solution is trade-specific, risk-led, and regularly updated as the business evolves.
FAQs
Why does sector risk matter more than business size for insurance?
Insurers often start with the nature of the work because it affects the likelihood and severity of claims. A small business in a high-risk trade can create more exposure than a larger office-based company with relatively low physical risk.
What insurance do ZZP businesses commonly consider first?
Many ZZP businesses begin with business liability insurance because third-party injury or property damage claims can be expensive. Depending on the trade, they may also need professional liability, tool or equipment cover, cyber cover, income protection, and legal expenses insurance.
What usually increases MKB insurance costs as a company grows?
MKB insurance costs often rise when growth adds operational complexity, such as more staff, vehicles, premises, contracts, or higher-risk services. Claims history, subcontractor use, security controls, turnover, and payroll can also affect premiums and terms.
How can a business decide which cover is most relevant?
A practical method is to map three main exposure areas: liability, cyber, and income risk. This helps identify where financial losses would hurt most and makes it easier to prioritize cover that fits the actual business model.
Why do insurers ask for documents during underwriting?
Insurers use documents such as revenue figures, claims history, contract details, equipment values, and cyber controls to assess risk accurately. Clear records can reduce delays, improve pricing accuracy, and make renewals or policy changes easier.


Reacties
Een reactie posten